burtongertrude
About burtongertrude
Time-examined Ways To Homes
 There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
 The arithmetic here is brutal and worth understanding clearly. A buyer who financed a $400,000 home at three percent in 2021 pays roughly $1,686 per month on principal and interest. That same loan at a seven percent rate costs $2,661. That gap of nearly a thousand dollars a month is why transaction volume has fallen to levels not seen in decades. Volume collapsed. Prices mostly did not.
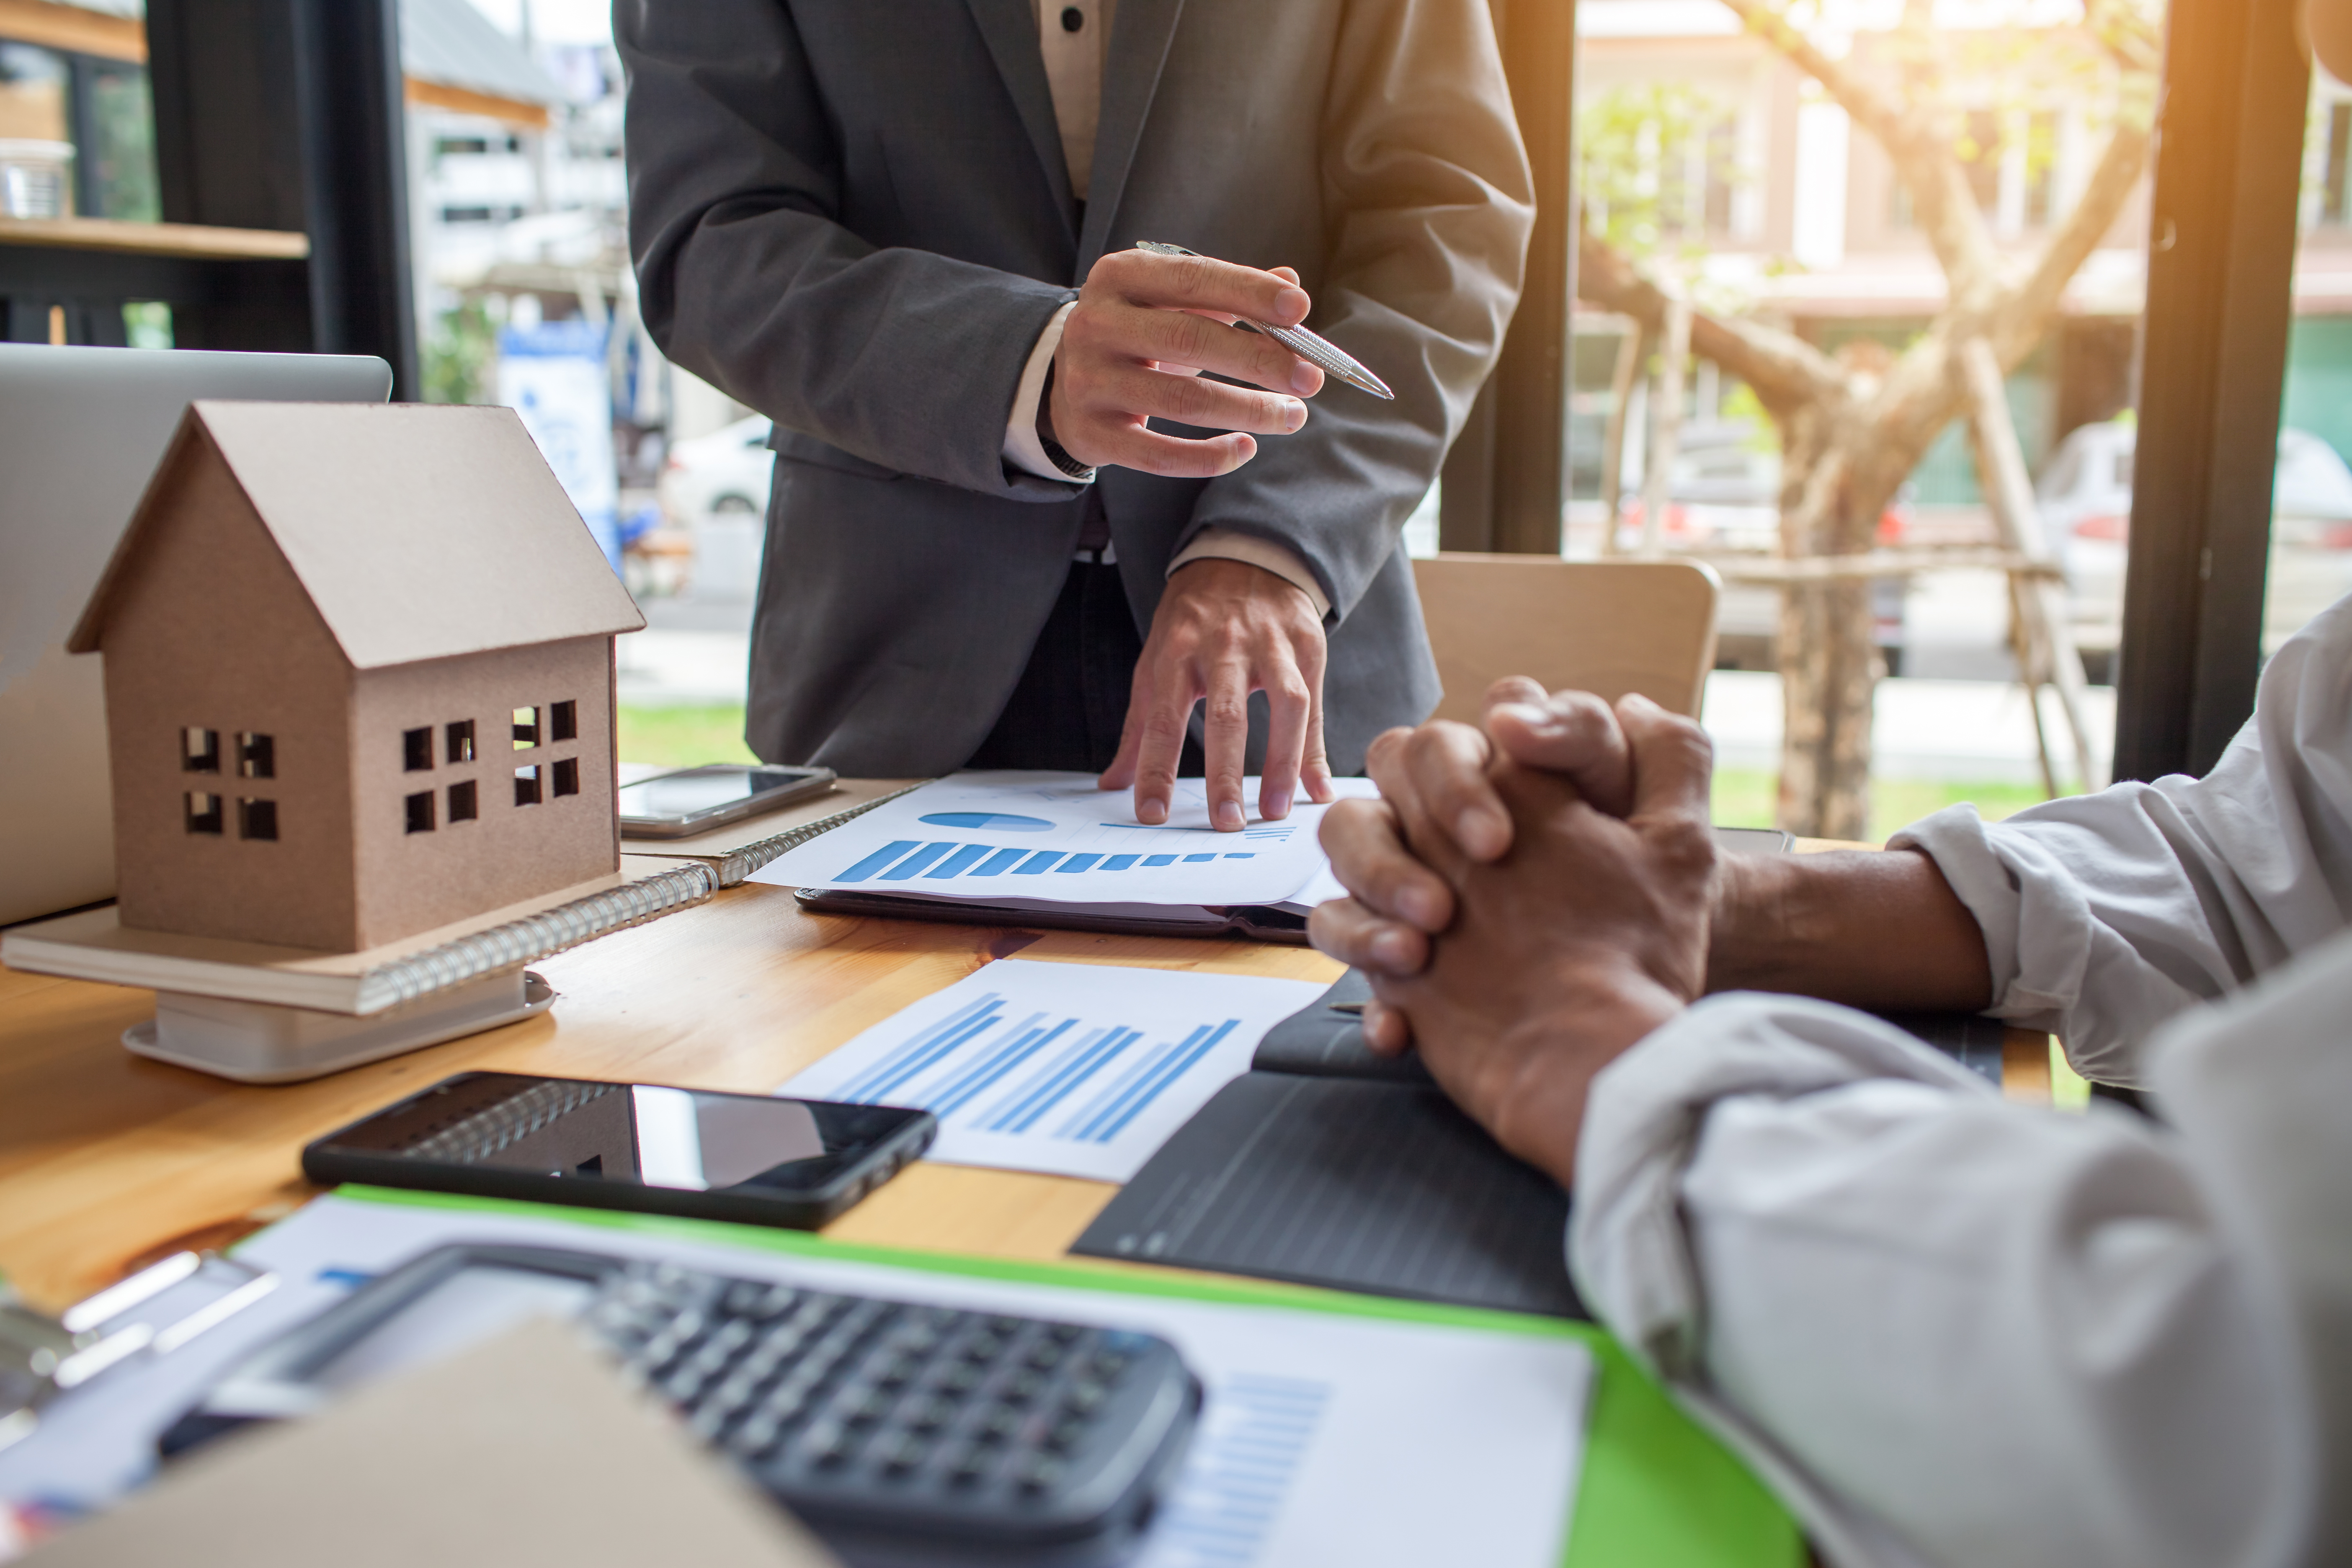 Here is what that creates for someone who is financially prepared and ready to move: more room to negotiate than the market’s reputation suggests. The panic buyers are gone. The buyers who showed up with emotion instead of analysis have mostly sat back down. What remains is a more functional market, even if it is not a cheap one.
Shop more than one institution, because the spread in rates and costs is real. A 0.25 percent gap between two lenders’ quotes adds up to real money that most buyers leave on the table by taking the first offer they receive. Lender fees vary too. Do not compare rate quotes without also comparing origination fees, points, and closing costs.
The appraisal is the lender’s check, not yours. When the appraisal comes in below contract, the deal does not automatically die, but it does require a decision. Ask your agent whether recent comparable sales support the price you are offering.
Budget between two and five percent depending on your loan type and the state you are buying in. First-time buyers are sometimes surprised by how much cash is required beyond the down payment itself. Ask your lender for a Loan Estimate as early in the process as possible.
The timing question, whether to buy now or wait for rates to come down, is the one that trips up more buyers than any other single factor. The record on market timing for owner-occupied housing is not encouraging. The more useful question is not whether now is the right time in the abstract; it is whether you are buying because the numbers make sense for you, not because you feel social pressure to own.
 Real estate rewards preparation more than it rewards timing. Waiting for a better market is a reasonable position only if your personal situation supports it, otherwise you are just paying rent while prices hold. Check up-to-date property listings and see whether what is available matches what you have been planning for.
No listing found.